Minnesota bankruptcy help
I gave my car back.
Why do I still owe money?
The car is gone. The debt may still be here. But you may have a way forward.
If your lender is demanding payment after repossession or voluntary surrender, Harmoning Law can help you explore whether bankruptcy makes sense for your situation.
Talk with attorney Matthew D. Harmoning about your options.
Why a balance remains
The sale pays down the loan.
It may not pay it off.
The lender applies the sale proceeds to the debt and permitted expenses. If there is a shortfall, it may seek the remaining balance from you.
The amount demanded is not automatically correct. The sale, notices, charges, and loan records may matter.
You do not need to sort through all of that before scheduling a bankruptcy consultation.
A possible fresh start
Can Chapter 7 eliminate the remaining car debt?
In many cases, yes.
An ordinary car-loan deficiency can generally be discharged in Chapter 7. Eligibility, exceptions, and the rest of your finances still need review.
We’ll consider your other debts, income, property, and deadlines to determine whether bankruptcy appears appropriate.
Questions on your mind
When the car is gone,
what happens next?
Collection letters, court papers, and concerns about your next paycheck can make the problem feel urgent.
Have a court date or response deadline?
Mention it when you contact us. Planning bankruptcy does not suspend a deadline.
Can the lender sue me after I give the car back?
It may sue to collect a valid deficiency. A demand letter is not itself a judgment. Tell us if you have received court papers.
What if I already have a court date?
Do not assume the hearing is canceled. Continue addressing deadlines and appearances unless the court or your attorney confirms otherwise. Tell us about the date when scheduling.
Does hiring a bankruptcy lawyer stop collection?
No. Filing generally triggers the automatic stay, which stops most collection activity. Exceptions and repeat-filing limits can apply.
Can this affect my wages or bank account?
A collection judgment can lead to garnishment, subject to applicable protections. Bankruptcy generally stops most garnishments while the automatic stay is in effect.
Does a discharged debt come back later?
A discharge generally ends your personal liability for a covered debt. Selling it to another collector does not revive that liability. If collection continues, contact your bankruptcy attorney.
What happens to the vehicle I drive now?
Keeping another vehicle depends on equity, available exemptions, and any loan or lease. We’ll discuss it before recommending a path; filing does not guarantee you can keep every asset.
Are payment plans available?
Harmoning Law offers attorney-fee payment plans. We’ll discuss the fee, court costs, and requirements for filing during your consultation.
Your first step
A conversation. A clearer plan.
01
Tell us what happened.
Discuss the vehicle balance and any collection letters, lawsuit, or upcoming deadline.
02
Look at the whole picture.
We’ll talk about other debts, income, and property—not just the car loan.
03
Understand your options.
Get a recommendation about whether bankruptcy appears appropriate and what comes next.
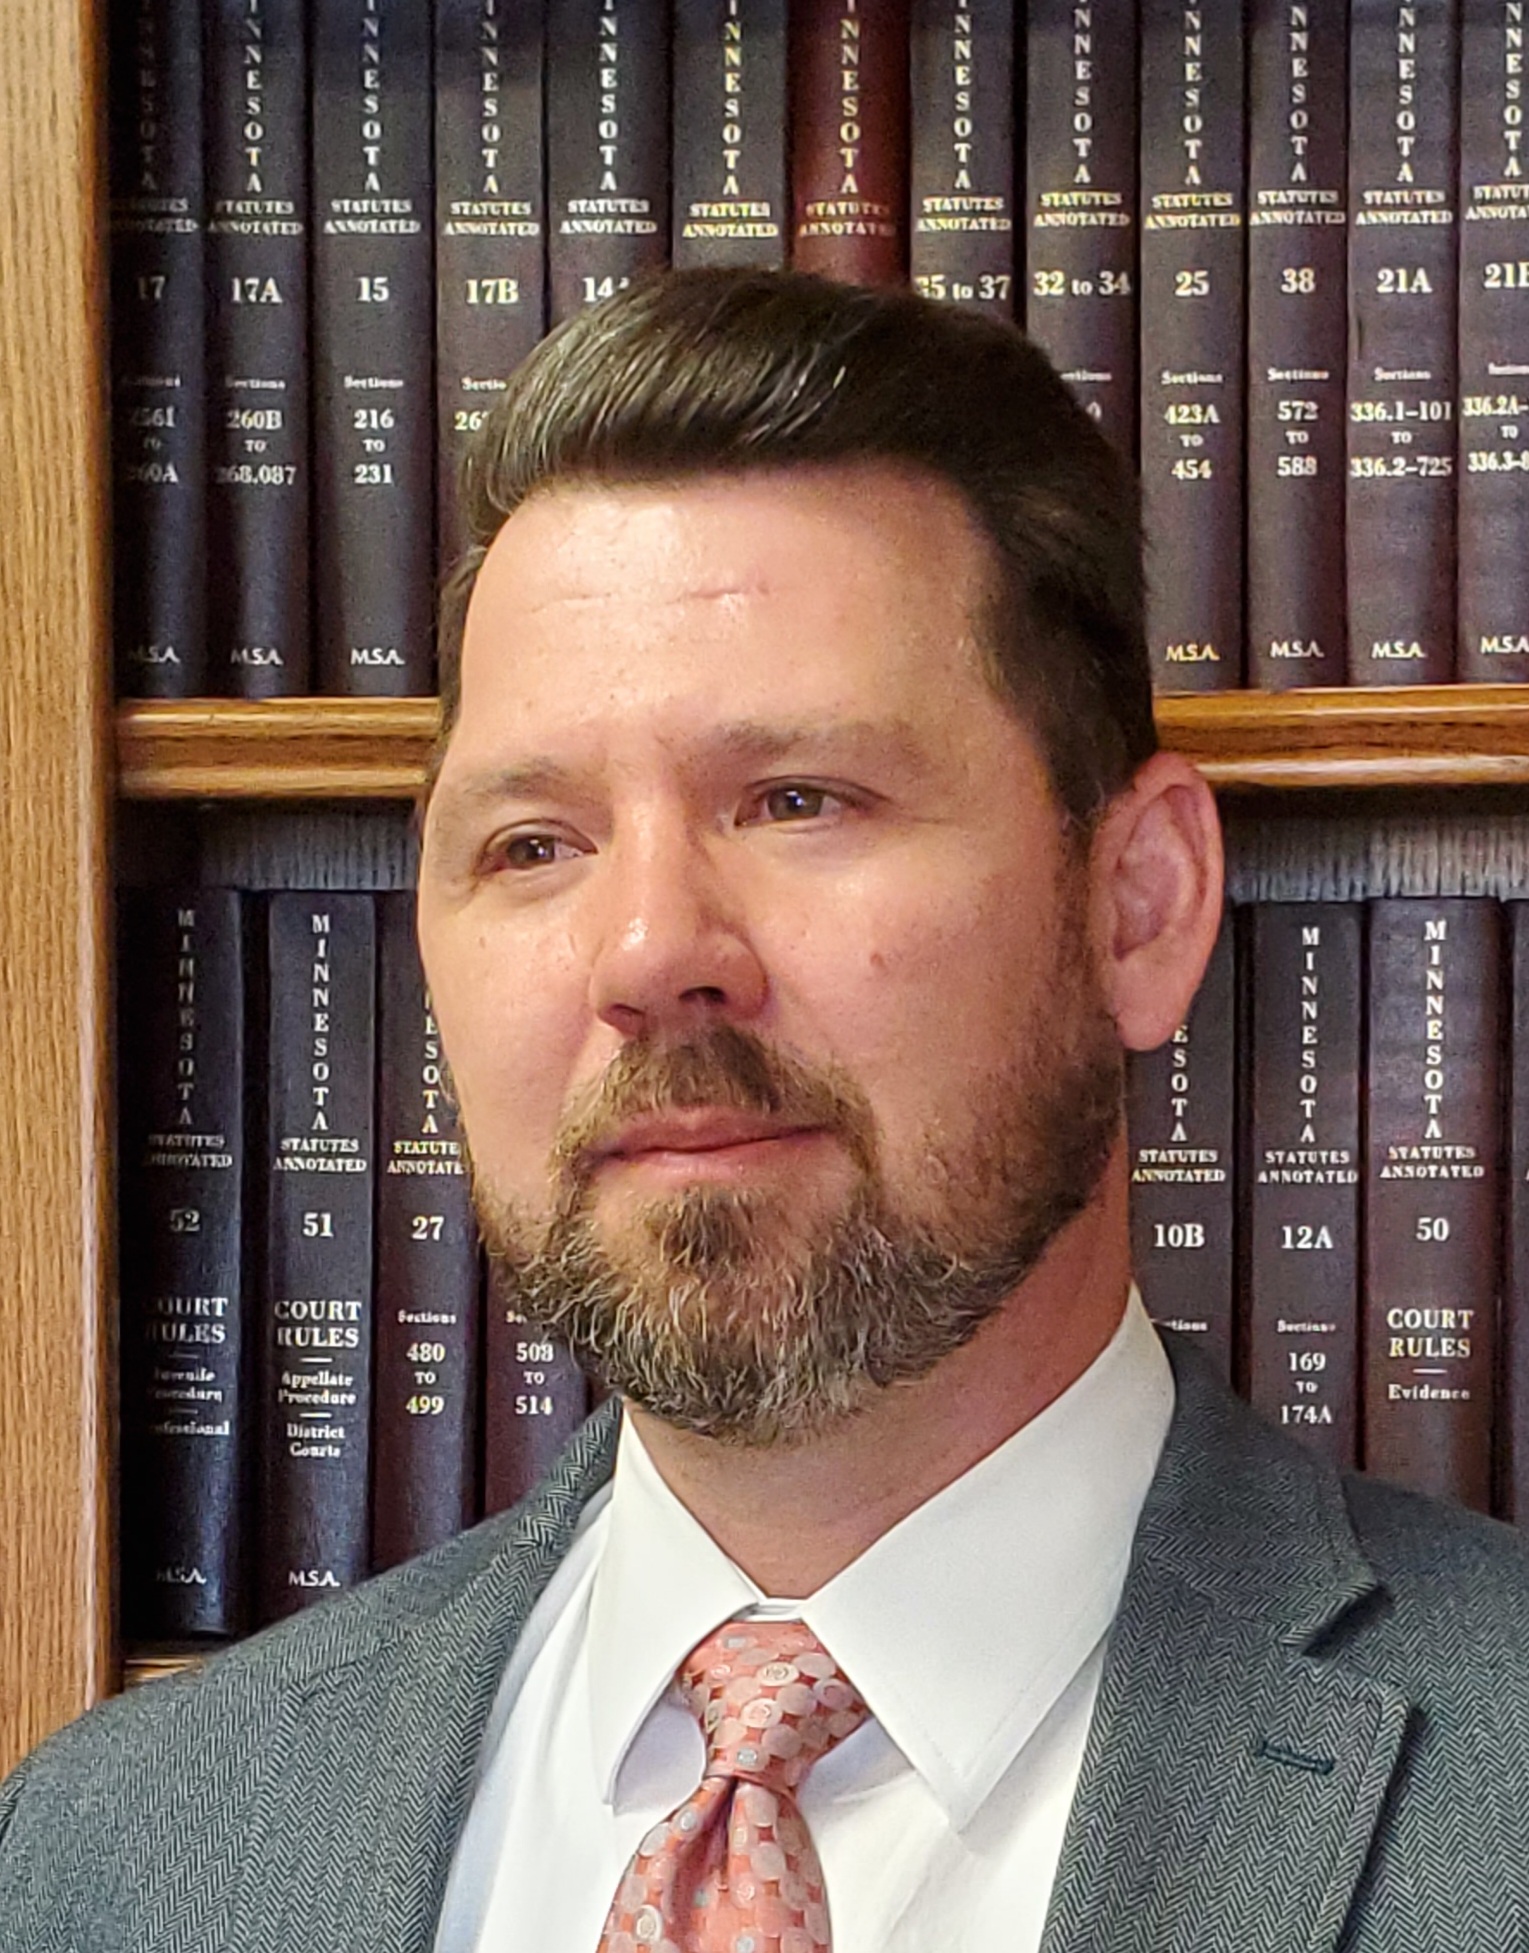
Meet your attorney
Matthew D. Harmoning
Harmoning Law PLLC · Minnesota bankruptcy attorney
You deserve a clear explanation of your options and a practical recommendation based on your situation.
Our consultation starts with what brought you here. You do not need to understand bankruptcy before we talk.
End debt stress. Start fresh.
The car is gone.
Find out what can happen to the debt.
Take the next step toward understanding your options.
We are a debt relief agency. We help people file for bankruptcy relief under the Bankruptcy Code.