Minnesota debt-collection lawsuits
You’ve been sued for a debt.
What happens now?
Start with the papers and the deadline. Then look at your options.
Do not ignore a summons or complaint. A timely response may protect your ability to contest the claim. If the debt is part of a larger financial problem, bankruptcy may offer another path.
Free bankruptcy consultation. Attorney-fee payment plans available.
Your first steps
Keep the papers. Identify the deadline. Get direction.
01
Save what you received.
Keep the summons, complaint, envelope, and any hearing notice. Write down when and how you received them.
02
Check what response is required.
District-court lawsuits and conciliation-court cases follow different procedures. An answer generally must be served on the plaintiff or its attorney; court filing requirements also need review.
03
Look beyond this one debt.
Consider the claim, possible defenses, other debts, income, assets, and collection pressure. The best next step depends on the whole situation.
Calling the creditor, negotiating, or scheduling a consultation does not by itself extend a response deadline. Missing the required response can lead to a default judgment.
Understand the possible paths
Responding to the claim. Addressing the debt.
The lawsuit itself
Questions about the creditor’s claim, the amount, service, or a possible defense may affect how you respond. Settlement may also be an option, but a negotiation is not a substitute for meeting a deadline.
If you want to contest the lawsuit, seek advice about the response and any defense. During an HL bankruptcy consultation, we assess whether bankruptcy appears appropriate and clarify what additional help may be needed.
Bankruptcy as a broader solution
Filing bankruptcy generally triggers an automatic stay that stops most ordinary debt-collection lawsuits while the stay applies. Booking a consultation or hiring an attorney does not trigger that protection.
Chapter 7 may discharge eligible unsecured debts. Chapter 13 uses a court-approved repayment plan. Eligibility, property, debt type, and prior filings affect the recommendation.
Bankruptcy does not stop every proceeding or eliminate every debt. Recent bankruptcy cases can affect the stay. A discharge also does not automatically remove every judgment lien.
Questions after being served
Know what needs attention now.
The papers have no court file number. Are they fake?
Not necessarily. In Minnesota, a civil lawsuit can begin through service before the papers are filed with the court. Lack of a file number or court stamp is not a reason to ignore them.
Do I always have 21 days to respond?
No. The usual district-court answer deadline is 21 days after service, but exceptions and different procedures apply. A waiver of service can change the deadline. Conciliation court uses a different process; follow the hearing notice and applicable rules.
Does a bankruptcy consultation stop the lawsuit?
No. The automatic stay generally starts with the bankruptcy filing. Unless applicable protection is in place or the deadline is properly changed, keep meeting the lawsuit’s response and hearing requirements.
What if I think the debt is wrong?
Save the papers and any records supporting your position. Possible defenses and the response deadline need attention even if bankruptcy is under consideration. Disputing a debt by phone does not replace a required legal response.
Is it too late if there is already a judgment?
Not necessarily. Bankruptcy may still address a dischargeable debt after judgment. Judgment liens and existing collection measures require separate review; a discharge does not automatically erase every lien.
Could the lawsuit lead to wage garnishment?
A judgment can lead to collection efforts, including garnishment, subject to legal limits and exemptions. Read about Minnesota wage garnishment if withholding has begun or you have received a notice.
The lawsuit is for a car I gave back. Why is there still a debt?
The vehicle’s sale may not have covered the loan balance and allowed charges. Read about repossession and voluntary-surrender debt, then bring the lawsuit and account records to your consultation.
What should I bring to the consultation?
Have the lawsuit papers, the date and method of service, any court notices, and a general picture of your debts, income, and property. You do not need every financial document ready to start talking.
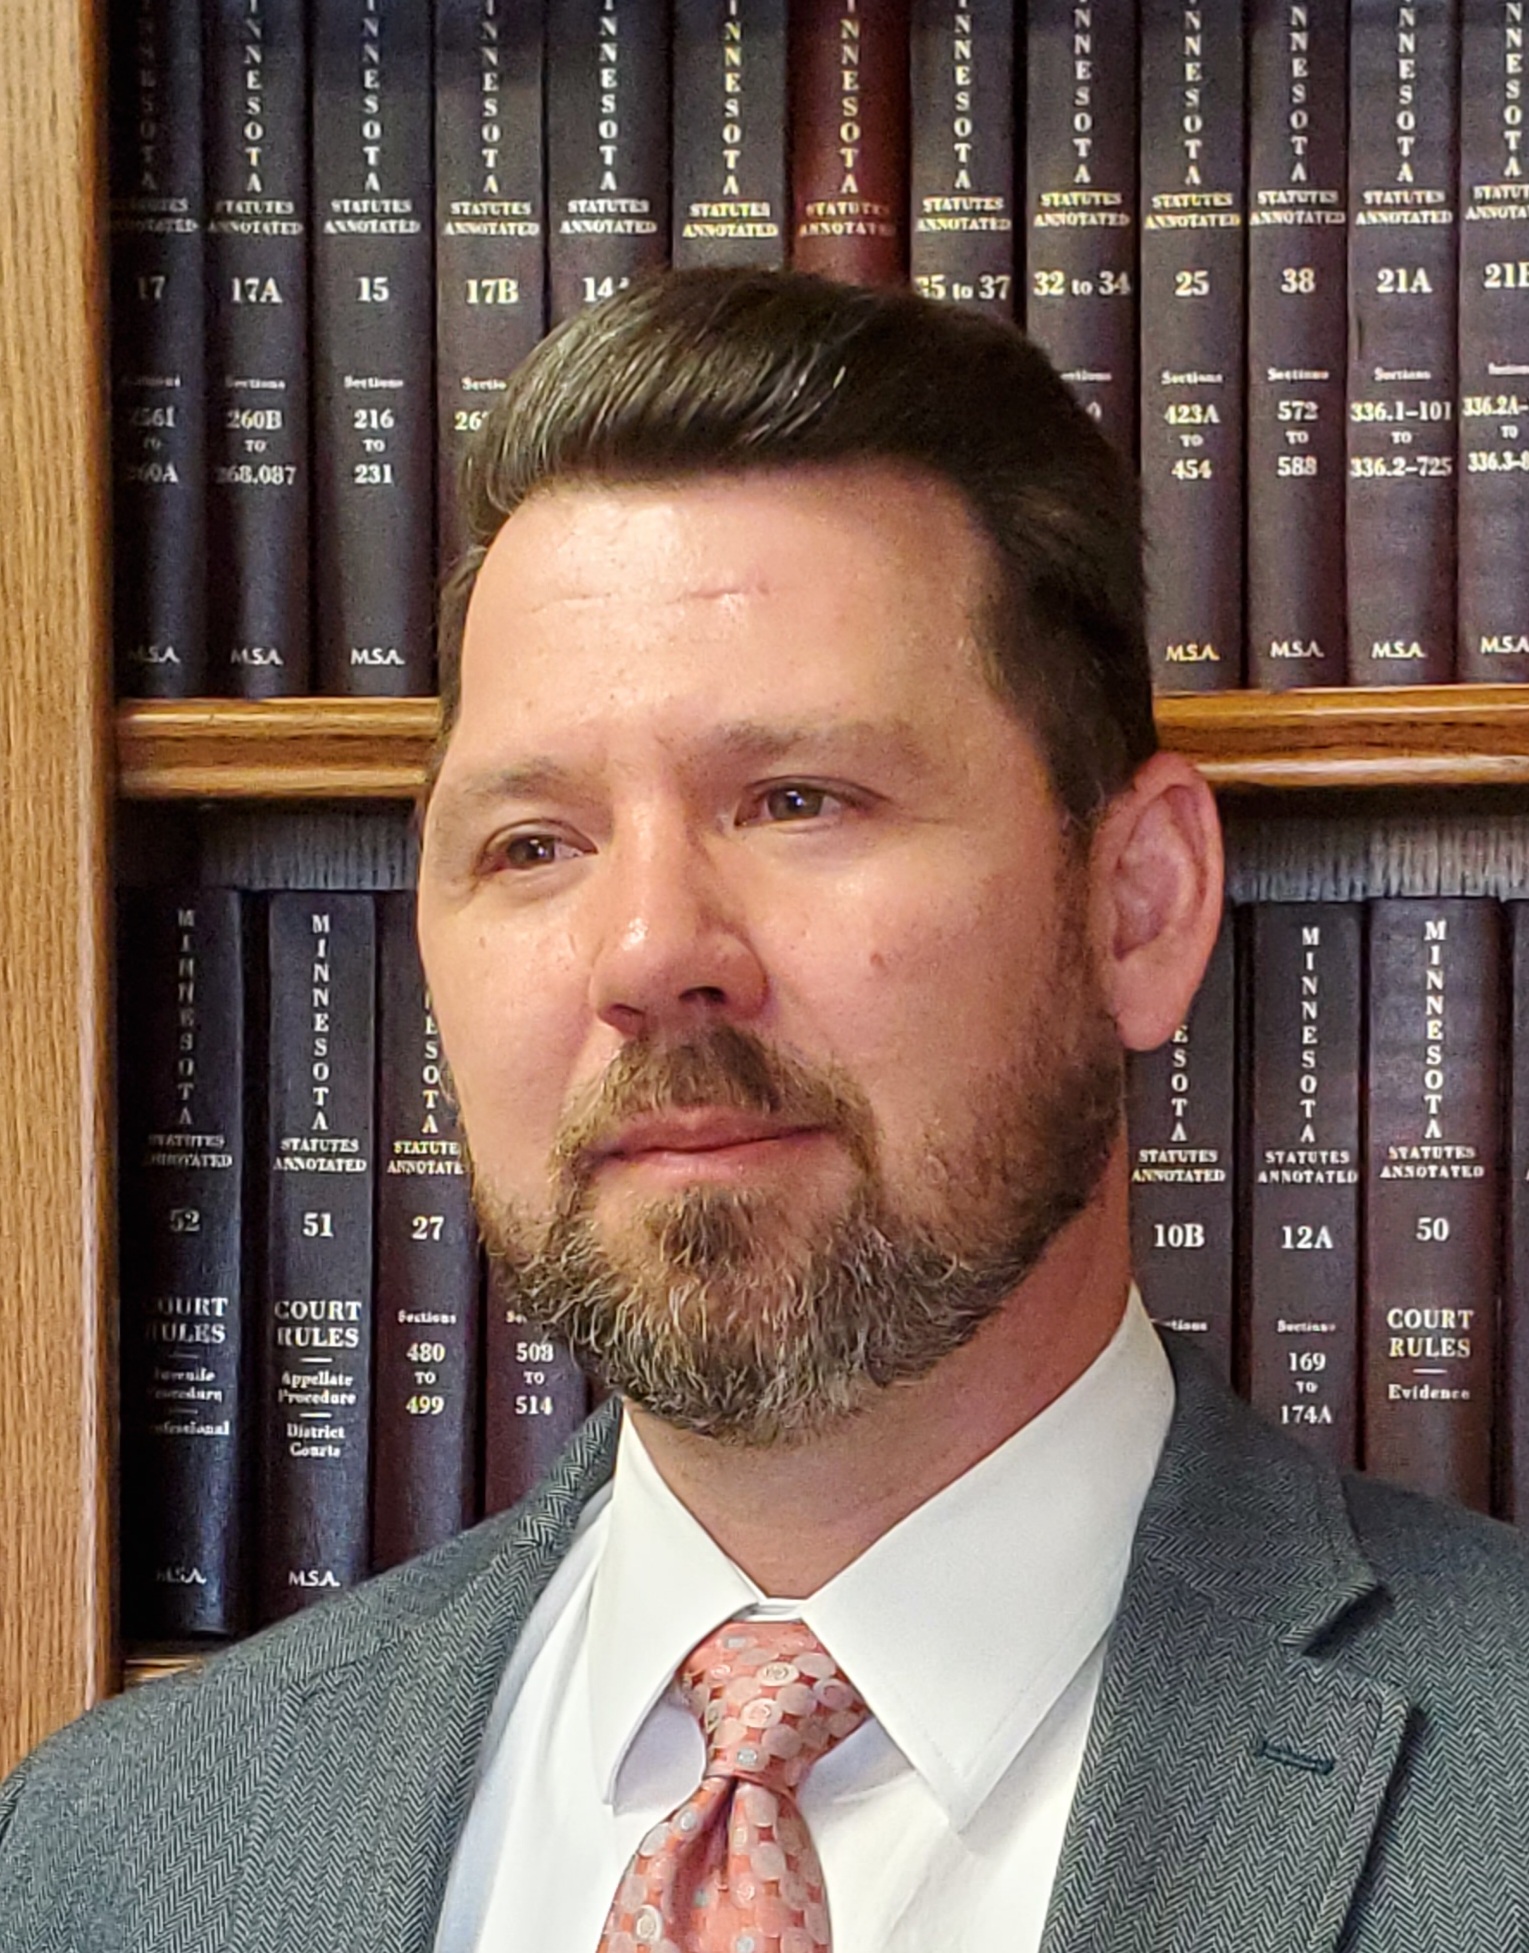
Meet your attorney
Matthew D. Harmoning
Harmoning Law PLLC · Minnesota bankruptcy attorney
You deserve clear guidance, respectful conversation, and a practical recommendation. Our consultation starts with your situation, not an assumption that you should file bankruptcy.
You do not need to understand the law or have every document ready before we talk.
End debt stress. Start fresh.
Understand your next step before the pressure grows.
Tell us about the lawsuit, any deadline, and your broader financial situation.
We are a debt relief agency. We help people file for bankruptcy relief under the Bankruptcy Code.